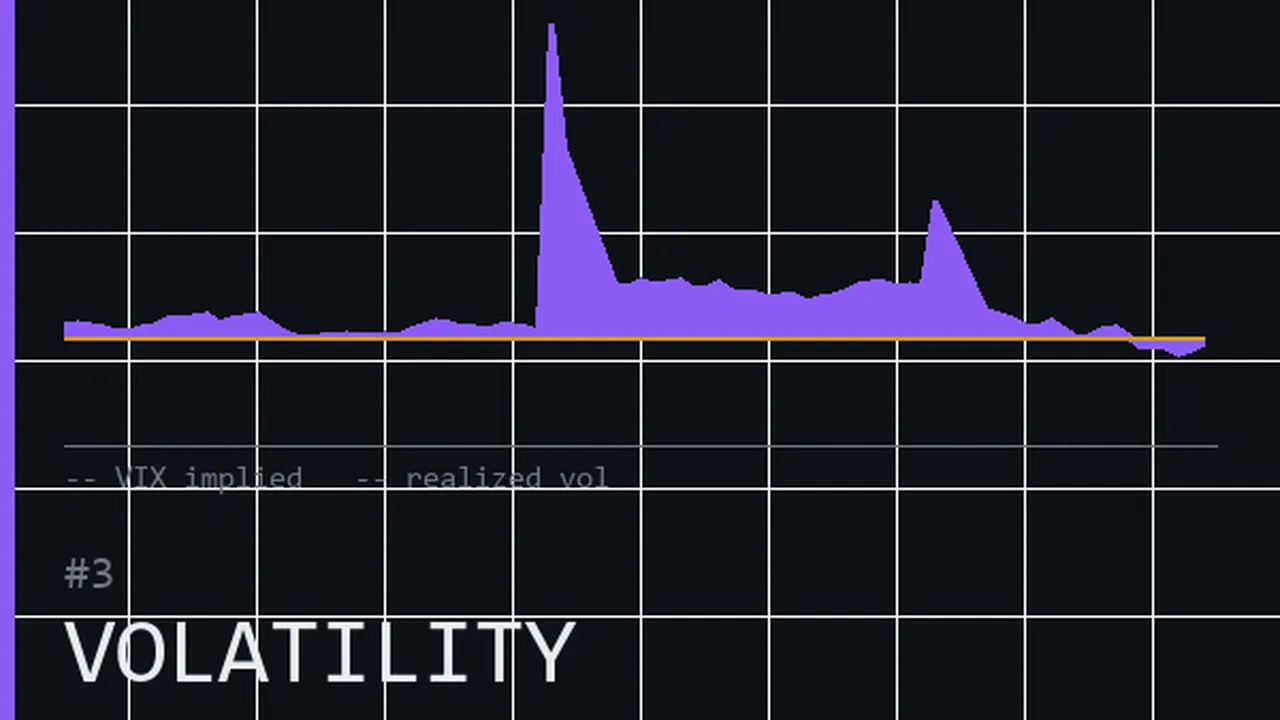
A systematic volatility mean reversion strategy using the VIX term structure spread against realized volatility.
What's included:
- Data: VIX, VIX3M, SPX from FRED + yfinance (free)
- Signal: standardized spread of implied vol vs realized vol
- VIX term structure visualization (contango/backwardation regimes)
- Three implementation approaches with risk/reward tradeoffs
- Backtest: daily signal, weekly rebalance, 2005-2024 (includes 2008, 2020, 2022)
- Vol-of-vol analysis (Sharpe undersells fat-tailed vol strategy returns)
- Sensitivity grid: realized vol lookback × signal threshold × position sizing
Who it's for: Options traders who want a systematic framework for decisions they're currently making discretionarily.
Not financial advice. Past performance does not predict future results.
TAGS: options, volatility, VIX, quantitative finance, python, jupyter, backtesting
Trading and quant
Volatility Mean Reversion Strategy
VIX Quant Notebook
A systematic volatility mean reversion strategy using the VIX term structure spread against realized volatility.
One-time price in US dollars, checkout by Stripe. After paying you land on a page with your download link. Each link works for 15 minutes, and reopening that page makes fresh ones.
- vol-mean-reversion-v1.0.zip